How to Record Down Payments and Advance Charges Correctly
◆ Payment & Ledger Tracking
How to Record Down Payments and Advance Charges Correctly
A down payment sets the tone for the entire installment plan that follows. Recorded incorrectly at the start, the error follows every installment after it.
The down payment is the first number in an installment sale, and it’s also one of the most commonly mishandled in manual record-keeping — not because it’s complicated, but because it happens fast, often at the same moment as the sale itself, with a customer standing at the counter and a queue behind them.
Why Record Down Payments and Advance Payments
A larger advance payment reduces the business’s risk on everything that follows — a customer with Rs 20,000 already invested in a Rs 100,000 purchase has a real reason to keep paying, in a way that someone who put down almost nothing doesn’t. Most Pakistani retailers know this instinctively, which is why 20-30% advance is common practice on phones, bikes, and electronics. What’s less consistently handled is recording that advance correctly once it’s collected.
How to Record Down Payments and Advance Charges
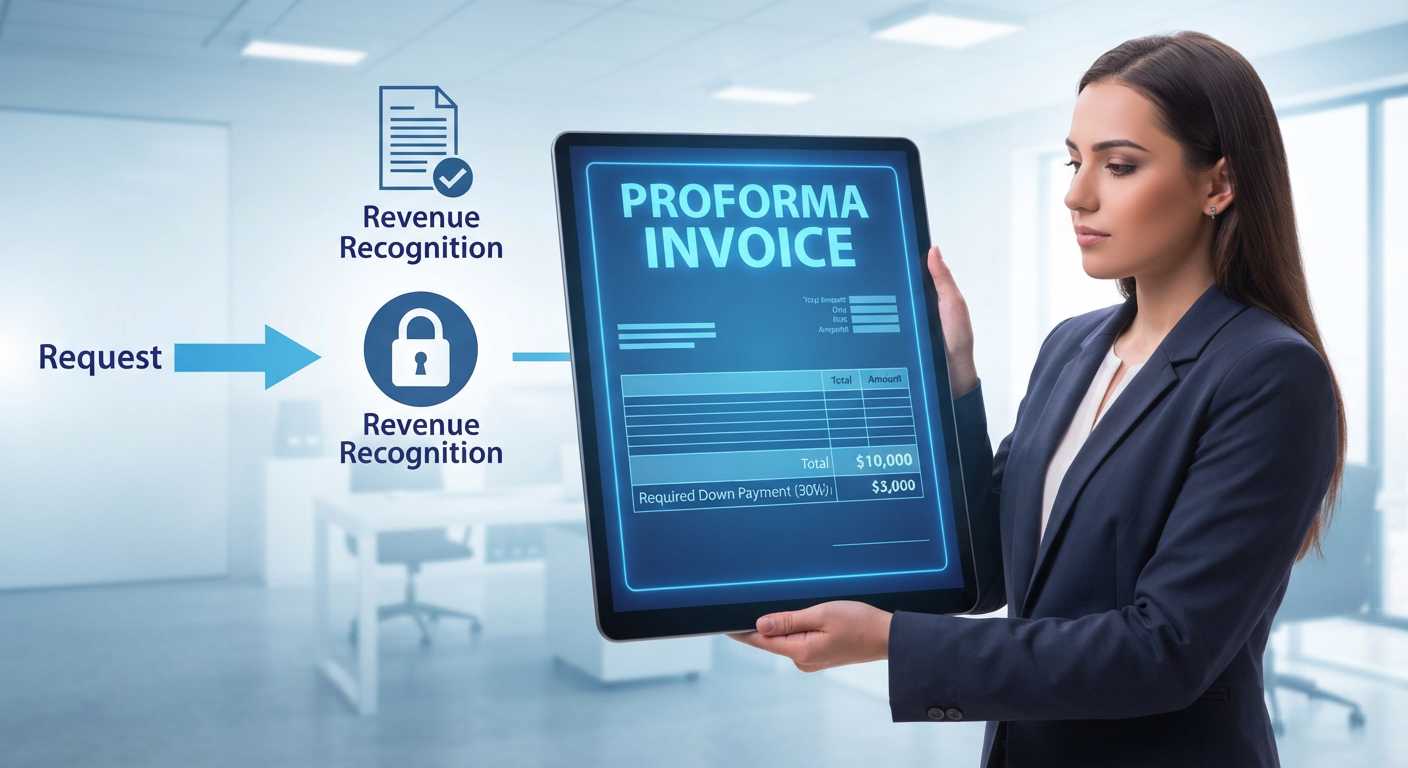
The installment schedule — how many payments, how much each one is — should be built on the balance remaining after the down payment, not the full price. Folding the down payment into the first installment, or treating it as a separate transaction that doesn’t reduce the schedule properly, is a common source of confusion. If the advance isn’t clearly subtracted first, the remaining schedule can end up either overstating what’s owed or under-collecting relative to the agreed installment price.
Down payment and installment price are two different numbers. The qist price — often higher than the cash price to account for the credit extended — should be agreed first, and the down payment subtracted from that figure, not treated as a discount off the cash price.
Benefits of Record Down Payments and Advance Entries
Beyond the down payment itself, some businesses charge a processing or documentation fee at the start of an installment plan — separate from both the advance and the regular installments. This needs its own line in the record, distinct from the down payment, since it typically isn’t refundable the way an advance sometimes is, and conflating the two makes any later dispute over what was actually paid and for what harder to untangle.
Common Mistakes in Record Down Payments and Advance Tracking
The most common failure isn’t a customer disputing whether they paid a down payment — it’s usually the business’s own records disagreeing with themselves. A register showing the down payment on one page and a separately calculated installment schedule on another, generated without properly accounting for that advance, can quietly drift out of sync. By the time anyone notices, reconciling exactly what happened at the start of a plan that’s been running for eight months is far harder than it would have been to record correctly on day one.
Best Way to Record Down Payments and Advance Transactions
Down payments and advance charges only happen once per installment plan, right at the beginning — which paradoxically makes them easy to handle carelessly, since there’s no ongoing routine forcing consistency the way monthly installment collection does. A business that’s disciplined about recording every advance the same way, every time, avoids a whole category of confusion that otherwise tends to surface months later, disconnected from the original sale and much harder to resolve with confidence.
Record Down Payments and Advance Before Schedule Creation
Down payments and processing fees don’t always carry the same refund terms, and this is worth deciding upfront rather than figuring out mid-dispute. Some businesses treat the advance as fully forfeited if a customer backs out early in the plan; others refund a portion after subtracting a cancellation charge. Whatever the policy, it should be written into the agreement at the point of sale and recorded consistently, not decided case by case depending on how the conversation with a particular customer happens to go. Inconsistent handling of cancellations is one of the more common sources of ill will between a business and its customers, precisely because it feels arbitrary from the customer’s side even when the business had reasonable logic behind each individual decision.
Keeping the record consistent across staff
In a business with more than one person handling sales, down payment recording is exactly the kind of task where individual habits quietly diverge. One staff member might fold the advance into the first installment’s total; another might record it as a separate line the way it should be. Neither is doing anything obviously wrong in the moment, but six months later, reconciling two customers’ accounts that were recorded differently is a real headache. A shared, enforced format — ideally one the recording system requires rather than merely suggests — closes this gap before it becomes a pattern across the whole customer base.
Down payments recorded correctly, every time
QistBook separates advance payments and fees from the installment schedule automatically, keeping every number consistent.
Frequently Asked Questions
What percentage down payment is typical for installment sales in Pakistan?
20-30% is common for retail items like mobiles, electronics, and bikes, though the right figure depends on the product’s resale value and how much risk the business is willing to carry on the remaining balance.
Should a down payment be recorded separately from the first installment?
Yes. A down payment reduces the total installment price before the schedule is generated, and should be recorded as a distinct entry rather than folded into the first monthly payment, to keep the schedule and the record consistent.
What happens if a down payment isn’t properly recorded?
The remaining balance and installment schedule can end up calculated incorrectly, understating what’s actually still owed or creating a mismatch that only surfaces when the customer disputes the final balance.